August 2026 Developer Sales: New Home Sales Slump as Launches Dry Up Amid Seventh Month
Research16 Sept 20267 min read

August 2026 saw developers’ sales fall 79.1% month-on-month (m-o-m) to 153 new private homes (excluding ECs) sold. The sharp decline was mainly due to the absence of major project launches amid the Hungry Ghost Festival in August.
New private home supply also fell by 87% m-o-m, with developers launching just 116 units in August, compared to the 889 units released during July. With limited fresh inventory available, both Dunearn House and Lentor Gardens Residences continued to lead new home sales since debuting in July.
In the Executive Condominium (EC) segment, 18 new units were sold in August, reflecting a 33.3% m-o-m decline from the 27 units recorded in the previous month. This marks the fifth consecutive month in which new EC sales have declined, following Rivelle Tampines’ launch in March. Developers also launched just 157 EC units in August.
Buying momentum in the EC segment is expected to pick up in 2027, with Wynwood Grand at Woodlands Drive 17 slated to preview by year’s end.
Table 1: New home sales over the last six months (excluding ECs)
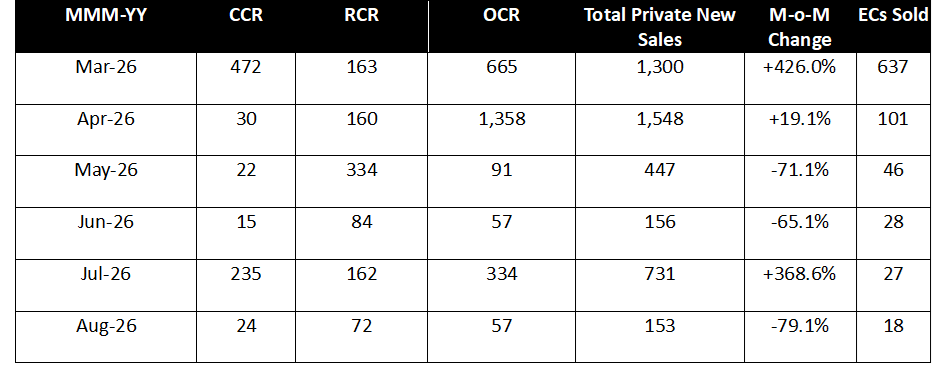
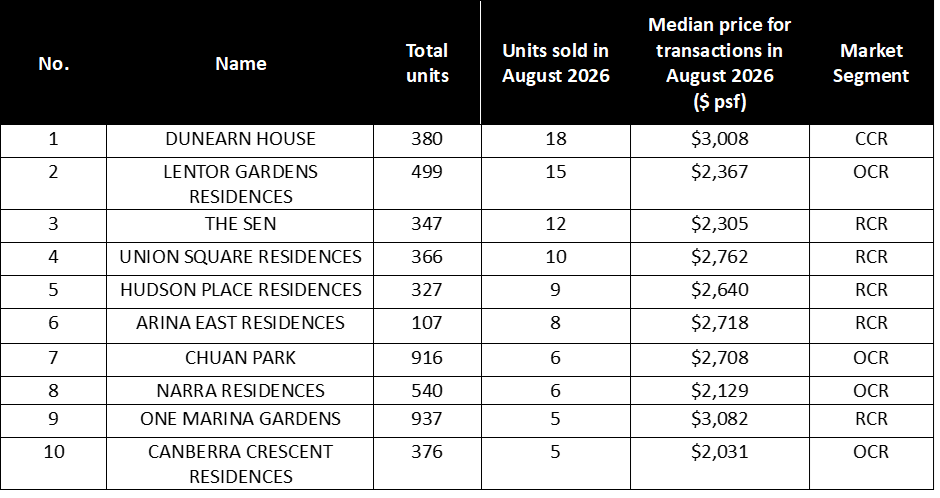
Table 2: Top performing new non-landed projects in August 2026 (excluding ECs)
Dunearn House Continues to Draw Homebuyer Interest
Dunearn House led new private home sales in August, recording 18 transactions at a median price of $3,008 psf over the month. Buyers likely saw this price point as offering reasonable value, as it hovers below the overall $3,059 psf median for new non-landed homes sold in the CCR, based on caveats lodged in August. This price gap may have helped seal the deal for some first-movers, especially those interested in Bukit Timah Turf City’s long-term potential.
Since launching in July, buyer interest in Dunearn House has been largely supported by future plans for the wider Bukit Timah Turf City precinct. Proximity to key transport links, such as Sixth Avenue MRT station on the Downtown Line (DTL) and the upcoming Turf City MRT station on the Cross Island Line (CRL), has also strengthened its appeal among buyers, including those targeting a first-mover advantage.
Lentor Gardens Residences Demonstrates Precinct Resilience
Lentor Gardens Residences was the August’s second-best performing project with 15 transactions at a median price of $2,367 psf. Sales in the month were evenly distributed across room types, with two-, three-, and four-bedders recording five transactions each. This likely reflects Lentor’s broad‑based appeal among HDB upgraders and right‑sizers from nearby public and private housing estates.
As the seventh launch within the Lentor residential estate, the project continues to benefit from the precinct's strong track record of near-complete take-up across its six prior launches dating back to 2022. Proximity to Lentor MRT station, reputable schools, and the precinct's visible development following the completion of Lentor Modern and its integrated mall, have supported steady interest across launches.
Of the six earlier launches in Lentor, only Hillock Green and Lentoria have stock remaining, with two units and 17 units unsold respectively as of end-August.
With the next launch at Lentor Central not expected to take place until 2H 2027, buyers seeking a home in the area are likely to turn to existing stock. This could help to drive steady take-up of unsold inventory at Lentor Gardens Residences in coming months as available options in the precinct continue to narrow.
Other Key Movers in August
The Sen, an RCR development in upper Bukit Timah, emerged as the month's third-best performer with 12 units sold at a median price of $2,305 psf. Units sold ranged from approximately 678 sq ft to 1,109 sq ft, with prices between $1.63 million to $2.60 million, based on August caveats.
This was followed by Union Square Residences, which moved 10 units at a median price of $2,762 psf, and Hudson Place Residences, with 9 units at a median of $2,640 psf.
Dwindling EC Inventory Sets the Stage for Wynwood Grand
In August, developers sold only 18 new ECs, representing a further 33.3% m-o-m decline from the 27 units recorded for July. Against a backdrop of shrinking new EC inventory, this is the segment’s weakest monthly performance so far this year, below even the 20 units sold in February.
Coastal Cabana continued to lead new EC transactions for the fourth consecutive month with 12 units sold at a median price of $1,830 psf. Rivelle Tampines, which launched in March, accounted for the remaining six new EC transactions for August with a median price of $1,944 psf.
Chart 1: Number of unsold EC units and EC units sold
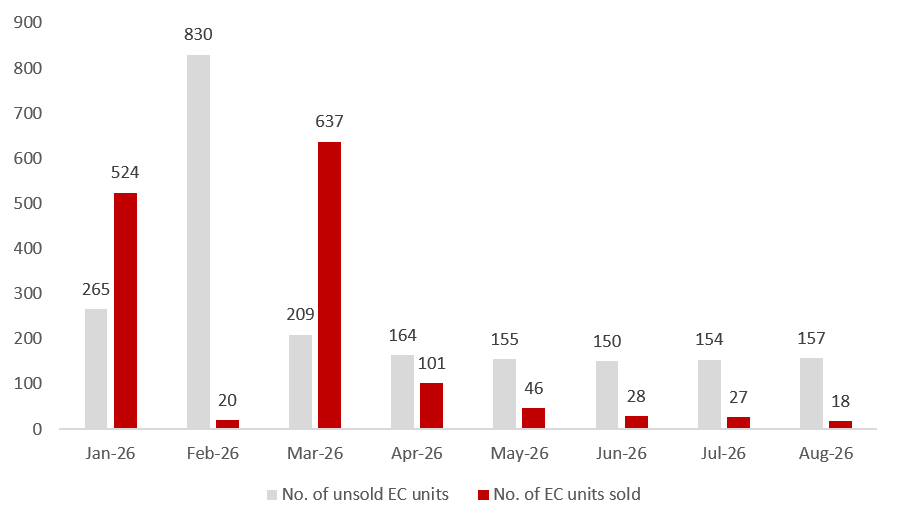
Based on developers’ sales records, only 157 EC units remain unsold as of August. This tight inventory is likely to keep new EC sales muted until future launches reignite buyer interest with fresh options in both layouts and locations.
Wynwood Grand, the next EC project to launch, is slated for a 4Q 2026 preview. It could draw strong interest from HDB upgraders and first-time buyers as the first EC development in the Woodlands planning area in more than a decade. The project will comprise 420 units and is among the last projects to come under the previous EC rules, including a five-year Minimum Occupation Period and access to the Deferred Payment Scheme.
Buyer Profile
Chart 2: Buyer profile for all new non-landed private homes (excluding ECs)
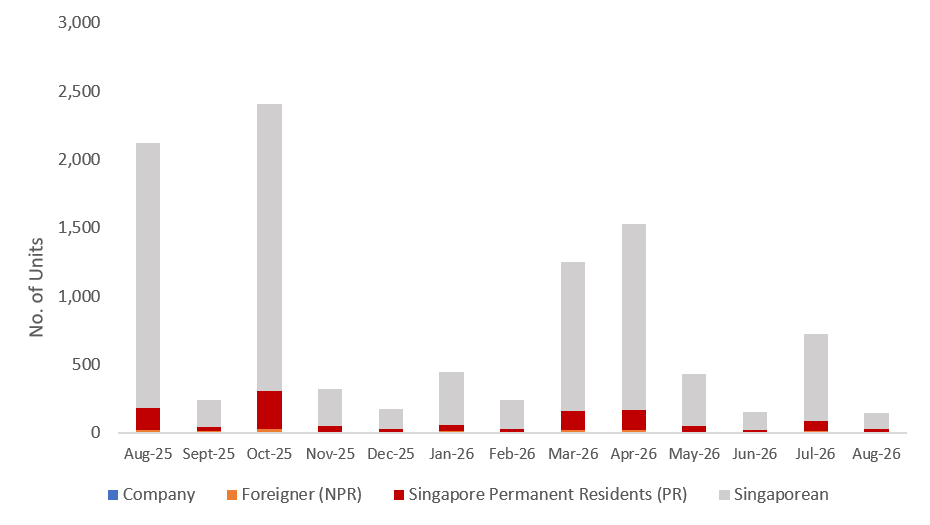
Singaporean Citizens continued to dominate new private home purchases in August, making up 85.2% of transactions, or 150 units, according to URA caveat data as at 15 September 2026. Permanent Residents accounted for 25 units, or 14.2% of transactions.
The 60% Additional Buyer’s Stamp Duty (ABSD) continued to dampen non-resident demand. Only one foreign purchase was recorded in August, representing 0.6% of total transactions, down sharply from 12 deals in July. Although foreign participation remained minimal, Singapore’s stable and transparent real estate market should continue to attract overseas buyer interest over the longer term.
Luxury Homes
Chart 3: Buyer profile for non-landed private homes (excluding ECs) transacted at $5mil and more
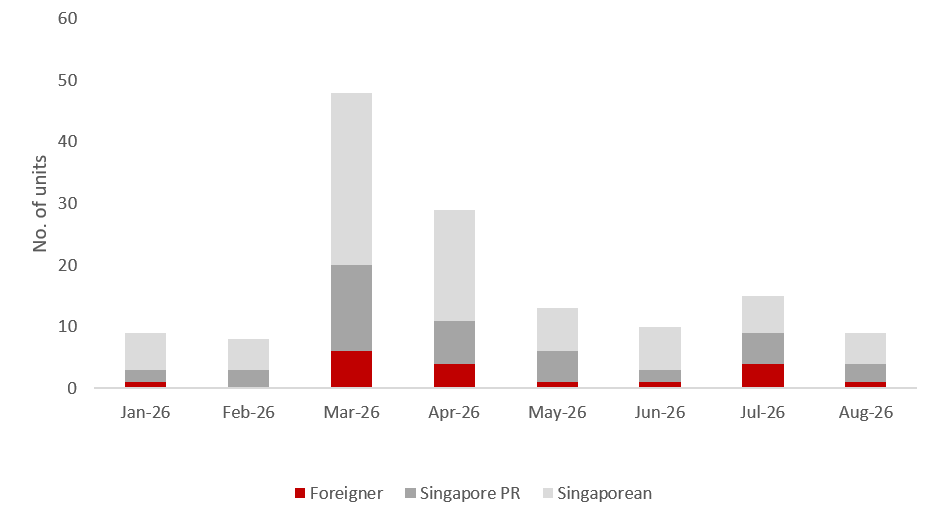
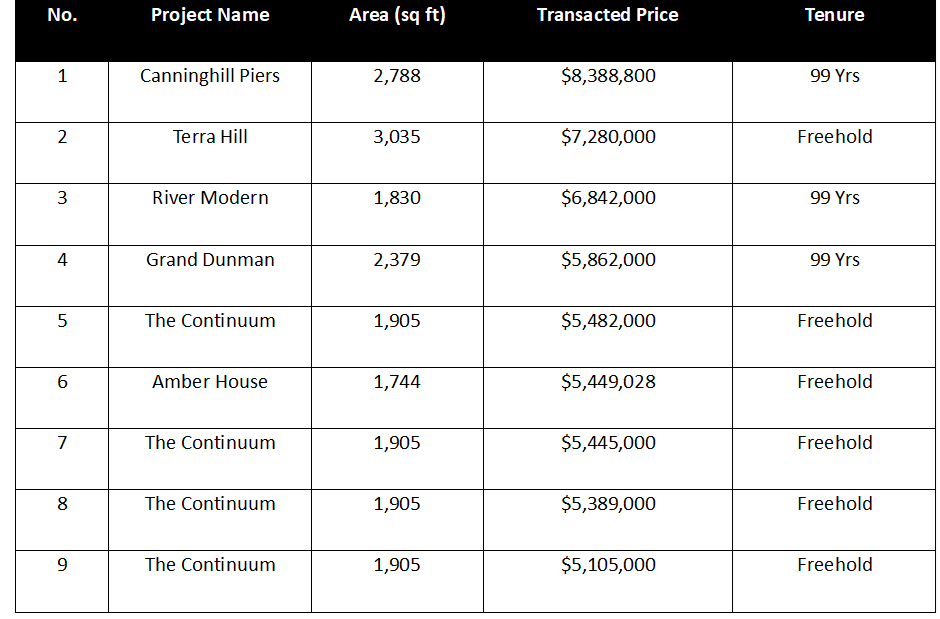
Non-landed luxury home transactions (excluding ECs) worth $5 million and above fell to nine deals in August, down from 15 in July. Singaporeans and Permanent Resident (PR) buyers accounted for eight of these deals, of which five were made by Singaporeans and three by PR buyers. The remaining luxury deal within the non-landed segment was made by a foreigner involving a four-bedroom unit (1,830 sq ft) at River Modern, which sold for $6,842,000.
Within the non-landed private home segment, the priciest transaction took place at Canninghill Piers, where a 2,788 sq ft unit sold for $8,388,800 ($3,009 psf) to a PR. Overall, the priciest deal involved a 2,959 sq ft semi-detached home at Gallop Park Road which was purchased by a Singaporean for $12.8 million ($4,326 psf).
Table 3: Top luxury non-landed private home (excluding ECs) transactions for August 2026
Closing Thoughts and Forecast
Earlier in August, the Ministry of Trade and Industry (MTI) adjusted its GDP growth projection upwards to 4.5% to 5.5%, higher than its previous projection of 2% to 4%. This improved outlook mainly stemmed from better-than-expected economic performance for 1H 2026, driven mainly by AI-related capital expenditure. Additionally, the economic impact of the ongoing conflict in the Middle East has also been less severe than expected, allowing Singapore’s GDP to grow by 6.1% y-o-y for 1H 2026.
At the same time, the real estate sector’s outlook remains positive, backed by attractive new condominium launches and firm buying interest. However, transaction volumes may be capped by a leaner launch pipeline, with an estimated 2,229 private residential units across five projects expected in 2H 2026. This is likely to constrain full‑year private home sales despite healthy underlying demand.
For September, both the re-launch of Belgravia Ace (23 units) and debut of Amberwood At Holland (230 units) could result in a modest pickup in developer sales. As the first private residential launch in Holland Plain, Amberwood At Holland may attract buyers seeking an early foothold in the area ahead of wider transformation.
Against this backdrop, ERA Singapore expects new private home sales (excluding ECs) to reach around 9,000 units by year-end, barring any unforeseen circumstances.